Bernardo
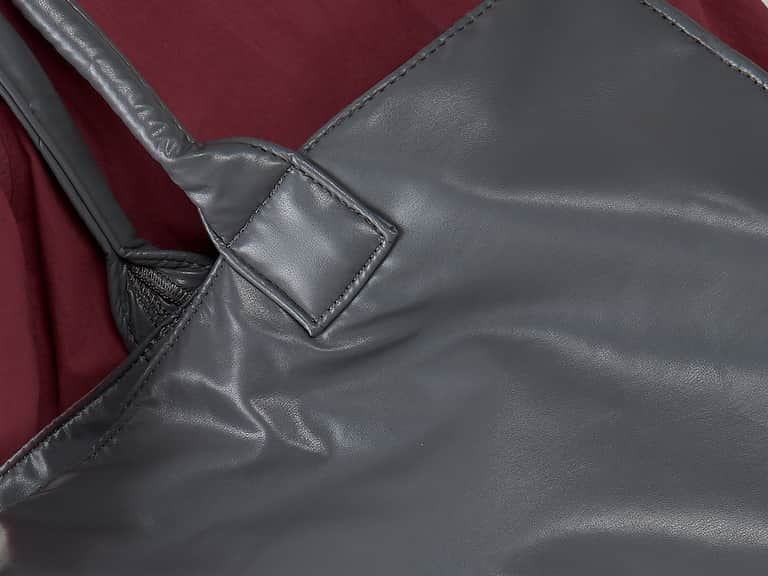
Keep garments wrinkle-free with a stylish valet stand: iron frame, stretchy nylon fabric supports bags and clothes in the center, machine-washable for easy care, plus a decorative touch in any bedroom.
A beginner-friendly exploration of debt concepts, repayment tactics, and the real-world choices people face when balancing borrowings. Through bite-sized scenarios and historical perspectives, readers learn how to navigate consolidation, snowball vs. avalanche methods, and mindful spending.
Debt is a fixture of modern life. It powers homes, education, and entrepreneurship, but it also imposes a cost—an ongoing reminder that the money today often comes with a price tomorrow. The journey to responsible debt management begins with clarity: understanding how interest compounds, recognizing your income and expenses, and identifying a strategy that aligns with your personal goals. This article, written in the time-honored cadence of thoughtful journalism, presents debt not as a stigma but as a set of financial tools—something you can learn to use with confidence.
Debt is a promise to repay borrowed money. When you borrow, you agree to pay back the principal plus interest. Interest is the price of time—the cost of having money today but paying for it in the future. The simplest way to visualize compounding is to imagine a snowball rolling downhill: as it grows, it picks up more material, and the amount of interest you owe grows faster over time. The key takeaway is that small, disciplined repayments can dramatically reduce the total interest paid over the life of a loan.
Consider a familiar scenario: you borrow $1,000 at an annual interest rate of 6%. If you pay only the minimum and allow interest to accrue, the total amount owed becomes significantly larger over a few years. If you instead commit to steady principal repayments, the debt burden shrinks more quickly. The math, while constant, becomes powerful when paired with real-life budgeting choices.
Two popular frameworks for repayment dominate personal finance discussions: the snowball method and the avalanche method. Each has distinct psychological and mathematical merits, and the best choice often depends on your unique finances and temperament.
The choice is not purely mathematical. It hinges on the intersection of math and behavior. A mathematical optimal path might not be the path you can stick to. The most effective plan is the one you can sustain, day in and day out.
Before diving into debt consolidation or strategic repayment, ensure you have a basic safety net—an emergency fund that covers three to six months of essential expenses. This cushion reduces the likelihood of slipping back into debt when unexpected costs arise. Simultaneously, assess your monthly budget to identify discretionary spend that can be redirected toward debt repayment. A stable cash flow makes any debt-management plan more resilient.
Timing matters. If your debts carry variable rates, promotional terms, or a potential change in income, a flexible plan becomes essential. The best plan blends discipline with adaptability, allowing for adjustments as life changes. The following sections present tangible scenarios that illustrate how different approaches play out in real life.
Each scenario spotlights a distinct financial reality, inviting readers to weigh options through a practical lens. We present the situations in concise vignettes with recommended considerations, followed by an analytical reflection that clarifies the path to debt reduction.
Alex, a recent graduate, carries a mix of federal and private loans. With a modest income and rising expenses, Alex considers consolidation to simplify monthly payments.
Key questions: Should consolidation reduce monthly payments or overall interest? Is it worth sacrificing some debt flexibility for easier budgeting? A practical approach begins by listing all debts, their interest rates, and due dates. If consolidation reduces monthly payments while preserving loan quality and forgiveness options, it could be a viable step. However, if it locks in higher long-term costs or reduces eligibility for benefits, other strategies may be preferable.
Priya faces high-interest credit card debt amid irregular income. She questions whether to pursue a balance transfer, a personal loan, or the snowball method to regain control.
Reflection: A balance transfer can reduce interest for a period, but fees and promotional terms must be weighed. The snowball approach might deliver quick wins that rebuild confidence, while the avalanche method targets the highest-rate balances to minimize total interest. The best path often blends strategies: transfer or refinance the highest-rate debts, while applying rapid payments to smaller balances to sustain motivation.
Jordan experiences a sudden medical bill. The question becomes: should the focus be on liquidating smaller debts first or stacking an emergency fund before aggressive repayment?
Takeaway: In emergencies, preserving liquidity often takes precedence. A modest emergency fund acts as a shield against new debt and can prevent the cycle from turning into a long-term burden. If possible, renegotiate terms or seek hardship programs for high-cost debts to maintain breathing room while gradually rebuilding resilience.
A recurring theme across all scenarios is discipline in everyday purchases. Small, intentional changes—like tracking discretionary spending, delaying nonessential purchases, and automating debt payments—can produce outsized benefits over time.
Bottom line: Debt management is not a single action but a habit formed by consistent choices. Each decision to reduce debt contributes to a broader sense of financial well-being and freedom.
Debt and personal finance have long been shaped by the decisions of remarkable individuals. Here are three figures from distinct periods who illustrate the universality of debt management—from pragmatic budgeting to strategic risk-taking.
Franklin, one of the United States’ founding thinkers, was a pioneer of practical frugality and disciplined budgeting. His emphasis on thrift, saving, and incremental self-improvement laid groundwork for modern personal finance principles. In his writings, he urged readers to “save what you can, invest what you have, and avoid debt where possible.” His approach to debt wasn’t merely about numbers; it was about shaping a habit that could empower a person to pursue opportunity without being shackled by costly obligations.
Mary Hunt highlighted the social and economic costs of debt for working families and promoted practical budgeting and thrift. Her legacy resonates with today’s emphasis on financial literacy: understanding credit, tracking expenses, and building reserves. Hunt’s work underscores that debt-management literacy is a societal good, not just a personal skill.
Orman has popularized accessible debt-management strategies for a broad audience. Her guidance emphasizes emergency funds, responsible credit use, and a proactive approach to paying down debt. Her work illustrates how modern media can translate complex concepts into actionable steps—an approach that aligns with BankersBag’s mission of making financial literacy engaging and practical.
Debt management should be actionable, not abstract. The following pragmatic steps can help readers apply the lessons of this article immediately:
Debt management is a journey anchored in ordinary decisions—groceries, energy bills, and occasional splurges. The goal is not to eliminate debt overnight but to cultivate a sustainable path toward financial resilience and freedom.
In a world crowded with obligations, a well-organized space can mirror a well-ordered budget. Meet Bernardo, a valet stand that combines form and function—an emblem of how intentional design supports daily discipline. While it serves as a practical piece for garments and bags, it also embodies a broader principle: keep your assets, commitments, and plans neatly arranged so you can respond to life’s demands with clarity and poise.
Valet stand on an iron frame with paired nylon fabric covers that join the backs. It supports garments and bags at the center, with machine-washable nylon fabric for easy care. A small but meaningful reminder that organization reduces friction in daily life.
Just as Bernardo keeps things tidy, a deliberate debt-management plan keeps finances orderly. When bills are visible, due dates are tracked, and balances are categorized, you reduce anxiety and increase the likelihood of timely payments, which in turn minimizes interest costs and protects your credit score.
This is not an endorsement for a product; it is a symbolic anchor for our broader narrative: meaningful tools, whether physical or financial, help you navigate life’s complexities with confidence. In BankersBag, we celebrate practical items and practical knowledge alike—tools that empower readers to build a sturdy shield against the unpredictable tides of debt.
Debt is not a fate but a set of choices. The decisions to consolidate, to snowball or avalanche, and to guard an emergency fund are not isolated moments but ongoing commitments. By understanding compounding, prioritizing affordability, and choosing a repayment approach that suits your life, you can transform debt from a burden into a transparent, manageable aspect of your financial story.
As this article closes, remember that debt mastery begins with literacy and ends with discipline. The BankersBag metaphor—an ever-expanding toolkit of knowledge—invites readers to curate their own pocket of financial wisdom: a curated, practical, and humane approach to money that makes sense in the tempo of daily life.
Published on September 22, 2026. This article is part of BankersBag’s ongoing series on financial literacy and practical money management.